

Sixty-seven thousand dollars split over thirty-six months is $1,861 a month. That is the whole payoff in one line, and it is a number a teacher can hit.
Most people assume a payoff that size means a lottery win, an inheritance or a six-figure job. My debt was $20,000 in credit cards, $7,000 in medical bills, a $10,000 car loan and $30,000 in student loans, all on an ordinary salary.
I teach seventh grade in a public school in Columbus, Ohio. My gross salary was $56,000 and my take-home pay was $4,050 a month. From September 2020 to August 2023 I cleared the full $67,000 with no windfall.
The plan was a sequence, not a miracle. Four balances on one sheet, $600 a month from tutoring plus $3,000 each summer from camp, a fixed $1,860 sent to debt every month, groceries held at $425, and a $1,000 buffer against surprises.
You can copy it. The sections ahead show the starting math, the budget, the payoff order and the setbacks. Start with the one-page debt sheet, then automate your first extra payment.
You are carrying the same kind of stack on a normal paycheck. Here is the version that works, in the order that keeps it alive.
| Debt | Starting balance | Payoff order | Months to clear | Main lever |
|---|---|---|---|---|
| Credit cards | $20,000 | 1st | 1–12 | Highest interest, freed minimums |
| Medical | $7,000 | 2nd | 13–17 | Sinking fund covered copays |
| Car loan | $10,000 | 3rd | 18–26 | Kept the used car, no upgrade |
| Student loans | $30,000 | 4th | 27–36 | Final-year raise went straight to it |
A Teacher's Salary Covered the Plan
A normal salary did cover it. My gross pay was $56,000 when I started in September 2020, which came to $4,050 a month after taxes and everything else came out.
Nothing extra arrived to help. No lottery ticket, no inheritance, no check from family. The gap between my income and my debt payments came from the same salary I had before I started, plus work I already knew how to do. That is the whole reason I think you can copy this.
Here is where the $4,050 went. Rent took $950. Utilities took $180. Insurance took $160. Gas for the car took $120. Food took $425. My phone bill was $45. Everything else, from haircuts to birthday gifts, sat in a $200 misc line.
Minimum payments on the four debts ran about $1,180. Rent plus minimums alone came to $2,130, leaving me just under $2,000 for everything else each month.
By my last year, a schedule change at school pushed my salary to $61,000. That raise did not change my budget. It went to the student loans instead.
What made the whole thing run was that my paydays never moved. I knew the exact date money landed, twice a month, and I could set transfers against those dates and trust them. A salary that arrives on a schedule is a tool, and I used it that way.
Your rent and your minimums set the size of the gap. Do that subtraction for your own numbers before anything else, because it tells you how much side work you actually need.
🧭 2 quick taps · about 20 seconds
What should you tackle first?
Three questions to match your debt mix to the right starting move.
Start with this question
- How much of your debt is credit cards? Most of it · A little or none
Then read the part written for you
- Build the $1,000 buffer first — Before you attack the cards, put $1,000 in a separate account. The first surprise then does not become a new balance. Start with $150 a month until it is filled. $1,000 Read: $1,000 Buffer Kept the Plan Alive →
- Clear the cards first — With a buffer in place, send every extra dollar to the highest-rate card. Clearing it frees the minimum and gives you momentum for the next balance. $680 extra/month Read: Payoff Order Went From Cards to Loans →
- Lock in a fixed automatic payment — Choose one extra amount you can send every payday and schedule it. Treat it like rent, not a leftover. Your steady income makes this easy to copy. $1,860/month Read: The Monthly Target Was $1,860 →
- Set a floor and sweep the rest — Pick a lower fixed payment you can always meet, then sweep each side payment to debt as it arrives. The floor protects you; the sweep accelerates you. $600/month side income Read: Tutoring and Summer Camp Added $900 →
The $67,000 Was Four Separate Debts
The $67,000 was four debts stacked together: $20,000 in credit cards, $7,000 in medical bills, a $10,000 car loan and $30,000 in student loans.
That total hid the real problem. Each one carried a different minimum, a different due date and a different consequence if I missed it. The cards charged the most interest. The student loans were the largest and the slowest. The medical bill had a collections threat I did not want to test.
The whole became manageable when I split it. I wrote each debt on one sheet of paper with its balance and its due date, four lines in a column. Adding them gave $67,000. Seeing them apart gave me a map.
That sheet decided timing. It showed me which payment had to leave first. It showed me which due date fell where in the month. A mental tally could not do that. Paper could.
Do the same with yours. Four debts or two, they still have separate balances, separate minimums and separate consequences, and one sheet is the first act that turns a single scary total into a list you can work down.
The Monthly Target Was $1,860
The number I paid was $1,860 a month, on average, for 36 months. The minimums across my four debts came to $1,180. That left about $680 a month as the money that actually attacked the debt and moved the dates.
I know that figure because I did the division early. $1,860 times 36 months is $66,960, and the gap between that and $67,000 is rounding. The target was never a guess. It was arithmetic I could check on the back of the same sheet that held the balances.
The part that made it work was that $1,860 never sat around waiting to be a leftover. My automatic transfers went out every payday, before groceries, before anything else. I treated the debt payment like rent: a bill with a date, not a good intention.
If your paychecks are steady like mine, copy the fixed target. If your income is uneven, set a lower amount that always goes out and sweep extra into the debt whenever a payment comes in. The bill-like treatment is the same either way.
Pick the figure that covers your minimums, add what you can truly commit, and put it on a schedule. The amount can change later. The automatic part should not.
How $67,000 became $1,860 a month
The arithmetic behind the payoff, with round numbers
Based on a $56,000 salary; final-year raise to $61,000 went to student loans.
Tutoring and Summer Camp Added $900
Tutoring paid me $600 a month during the school year. Summer camp work added $3,000 each summer. I built both out of the job I already had. No new credential, no second career, no night classes toward a different field. I sold the same seventh-grade teaching skill set twice more: once as one-on-one tutoring in the evenings after school, once as camp instruction in July. If you can explain a subject to a room of twelve-year-olds, you can explain it to one kid at a kitchen table.
The rule I set for every extra dollar was simple. It never touched the monthly budget. Tutoring money arrived on the 15th and the 30th, and both payments went straight to the cards before I ever saw the checking balance move. When a parent paid cash, it went into the same transfer that week. Camp pay in June went out the same day it landed.
That refusal is the part worth copying, and it is the part I nearly broke. The first summer I told myself the camp money was a reward for a long year, and I spent a chunk of it. The $1,860 target came up short that month. A side stream that raises your spending leaves the target unfunded, no matter how many hours you put in. I fixed the leak by deleting the account from my phone so I could not look at the balance and invent a reason.
So before you chase extra income, decide where it goes. Pick the destination now, not on payday.
⚠️ COMMON MISTAKE
Do not skip the buffer
Skipping the $1,000 starter buffer is the fastest way to restart a credit card balance. The first repair or copay goes on the card, and the payoff clock resets.
The Grocery Budget Did the Heavy Lifting
Groceries did the most work of any cut I made. I capped them at $425 a month, and the way I held that cap was cooking on Sunday for the whole week. Weekday takeout was the habit that had been eating the budget, and I replaced it with containers of rice, beans and chicken I portioned out on Sunday afternoon. It cost me about two hours. It saved the most money of anything I changed.
That isn't the only place the money came from. I kept my phone at $45 on a prepaid plan instead of the $90 I had been paying. Miscellaneous spending came down to $200. Together those small recurring trims freed about $350 a month, and that $350 went straight to the debt payment rather than to a one-time purge that would disappear by the next month.
The math is the reason. A one-time purge is a moment, while a recurring trim repeats every month. That is the whole difference. A $350 monthly cut is a $350 lever that pulls again in January and again in February, and every month it pulls is a month the $1,860 target gets funded without new side income.
Here is what I would tell anyone copying this. Start with the one category you spend on without thinking, cook for the week on a set day, and write down what the cap saves you. Then send that savings to debt on the same schedule. If $425 is too tight, set your own number and hold it. A smaller cap you keep beats a heroic one you abandon in three weeks.
💡 PRO TIP
Treat the side income as invisible
I never let tutoring money touch my checking account for spending. It went straight to a separate account linked to the debt, so I never saw it as available for groceries or a night out.
$1,000 Buffer Kept the Plan Alive
A car repair hit in month seven and cost $1,800. A medical bill came the next spring at $900. Both arrived during the payoff, not after it. Neither one went onto a credit card, and neither one restarted a balance. That isn't luck. It was a $1,000 starter emergency fund I built before I made a single extra payment, plus $150 a month I set aside for known costs like car repairs and medical copays.
A sinking fund is money you save a little at a time for a bill you know is coming. That's the $150 a month. A copay is the flat fee you pay at the doctor's office before insurance covers the rest. That's what the $900 bill was made of. The sinking fund was a planned bill, not savings left over after debt. I treated the $150 like rent and it left my account on the 1st.
The $1,000 came first for one reason. A surprise paid with a credit card is a new balance, and a new balance works against the payoff. The order matters more than the amount. Small buffer first, then the attack.
Now take your own insurance deductible and add the last car repair you paid for. That is your starter number. Send the first $150 this month.
Jargon, decoded
Payoff Order Went From Cards to Loans
I sent the first dollar to the credit cards. They went first because their minimums were the heaviest and quickest to free. That's the smallest amount the lender requires each month to keep the account in good standing, and on $20,000 across a few cards those minimums were a big slice of the $1,180 I owed every month.
Cards took months 1 through 12. The day the last card hit zero, roughly $400 a month of minimums came off my required list. That money did not become spending money. It rolled straight into the next balance, which is why the momentum was real and not just a feeling.
Medical came next, months 13 to 17. Then the car loan, months 18 to 26. Each one had a start month and an end month written on my sheet. A balance without a window is just a worry. A balance with a window is a task.
Student loans were last, months 27 to 36. In the final year a schedule change at school pushed my salary from $56,000 to $61,000. I did not adjust my budget to the raise. The whole difference went to the student loans, and they cleared on time.
You can copy the sequence. Cards first to free the minimums, then medical, then the car, then student loans. Set your own months around your own minimums, because yours will not match mine. One number to write down: your card minimums, added up. That total is what your first year buys back.
📆 The 36-month payoff sequence
Months 1–12: credit cards
Average of $1,667 a month to the cards. Budget after all bills and debt: $200 of misc spending.
Months 13–17: medical
Five months, so about $1,400 a month. The $1,000 starter fund was for this, not the cards.
Months 18–26: car loan
Nine months, about $1,111 a month. Skip if your car loan rate is under 4% — send that money to the student loans instead.
Months 27–36: student loans
The $3,000 camp money each summer covered two months of this leg on its own.
The Plan Required Saying No for Three Years
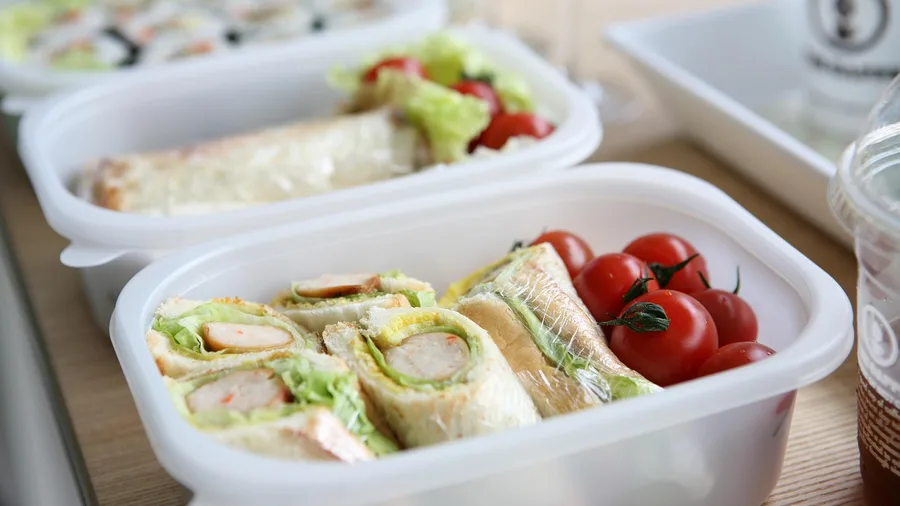
What I gave up was mostly small and mostly social. No vacations for three years. Packed lunches most workdays, sitting in the staff room with a sandwich while other teachers walked out for lunch. Nobody claps for that.
The bigger costs stayed fixed instead of creeping up. One streaming service, not four. A used car I already owned, kept running through the car-loan years instead of traded in. Upgrades are where a tight budget quietly loosens, so I just didn't make any.
The one thing I protected was $50 a month of fun money. It was mine, no questions, no tracking. That small allowance is why the plan lasted 36 months. A budget with nothing in it for you is the first thing you abandon, usually in month four.
Here is the honest trade-off. Some friendships got quieter during those years. I said no to trips and dinners and heard about it. But I still went to the cheap stuff, and the people who mattered understood.
Your version can be smaller than mine. Pick one recurring expense to cut, not five. Keep a fun line in the budget, even if it's $20. The restraint has to be one you can hold for years, not one that impresses for a month.
Two Setbacks Cost Weeks, Not the Plan
Even a budget with a little room in it runs into things. Mine hit two in the same stretch: a repair bill of $1,800 for my car and then a medical charge of $900. Neither was a catastrophe I saw coming; both landed mid-payoff, when a surprise could have broken the plan.
I checked what the sinking fund covered before I panicked. That account, fed by $150 a month, was built exactly for this, and it paid both without a single new credit card charge.
The debt-free date slid by about six weeks. Six weeks, not six months.
So here is the response that worked: look at what the buffer covers, add the gap to the calendar, and leave the automatic payment running through it. You don't restart. A surprise bends the timeline; it doesn't erase the plan.
Do this, not that
Kept the plan alive
- Automated the extra payment on payday
- Saved $1,000 before attacking debt
- Used a sinking fund for repairs and copays
- Kept $50 a month for fun
Killed the momentum
- Waiting to 'find' extra money each month
- Using credit cards for emergencies
- Raising spending when side income arrived
- A no-fun budget that gets abandoned
The First Move Is a One-Page Debt Sheet
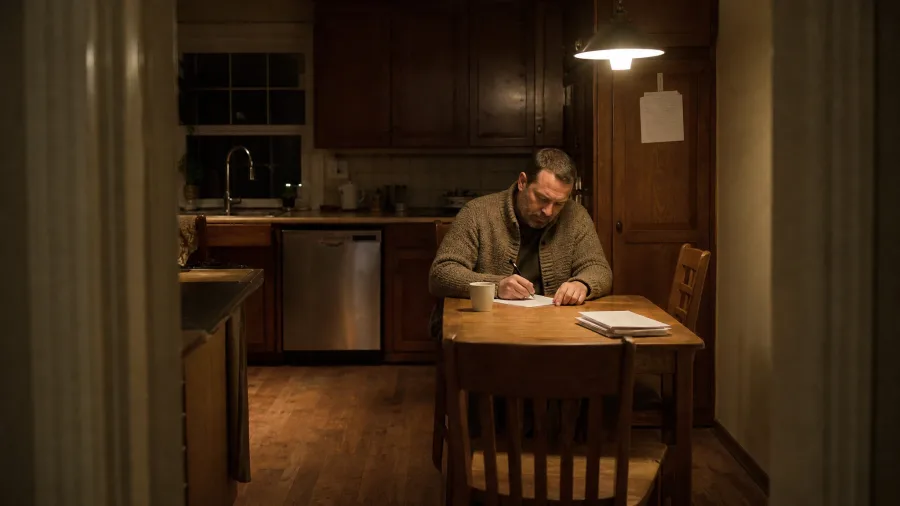
If a setback bends the plan instead of breaking it, the next move is to make every balance visible on one page. Not a mental tally. One sheet.
I used a single sheet of notebook paper, taped inside the kitchen cabinet where I'd see it before coffee. Four rows: balance, minimum, due date. Cards at $20,000, medical at $7,000, car at $10,000, student loans at $30,000, written out so the total and the order were both in front of me. The minimums added up to about $1,180 a month, and seeing that number next to my $4,050 take-home was the first time the payoff felt like arithmetic instead of panic.
Once the sheet exists, choose one extra amount that fits your budget and put the transfer on a schedule. Automate it. A remembered payment fails in a busy week; an automatic one does not.
Then set a check-in for 30 days out. Look at the sheet, adjust the number up or down, and keep going. The target is a dial, not a vow.
If you're a teacher like me, a fixed salary fits a fixed automatic extra payment. If your income moves around, set a lower fixed floor and sweep a slice of each side payment toward the sheet. Either way, the one-page sheet comes first.
The first version does not have to be right. It has to exist.
Frequently Asked Questions
How much extra did you pay each month above the minimums?
About $680 extra. The minimums totaled $1,180 and my average payment was $1,860. That extra $680 came from tutoring, summer camp and the grocery and phone cuts.
Did you use the debt snowball or avalanche method?
I used a snowball-style order by balance, starting with the cards. Clearing the cards first freed minimums and gave me momentum. You can use avalanche if the highest rate is not the smallest balance, but the sequence of cards, medical, car, student worked for me.
What if my income is not steady like a teacher's salary?
Set a lower fixed payment you can always meet, then sweep each side payment to debt as it arrives. The floor protects you; the sweep accelerates you. The one-page debt sheet still comes first.
How big should the emergency fund be before paying extra?
$1,000 was enough to keep me from using credit cards for the first surprise. After that, I put $150 a month into a sinking fund for car repairs and medical copays. If your income is very unpredictable, a larger buffer may fit you better.
Did you ever feel like quitting?
Yes, especially in the second year when friends were taking trips. Keeping $50 a month for fun and reviewing the debt sheet once a month helped. The plan bent with two setbacks but did not break.
Fill in the sheet this week and automate one extra payment
Here is the verdict. Four balances stayed visible on one page, extra work added $600 a month and $3,000 a summer, $1,860 a month went out automatically, and $1,000 plus $150 a month soaked up the shocks. That cleared my $67,000 in thirty-six months on a teacher's pay.
You start where I started: credit cards, medical bills, a car loan, student loans, one ordinary salary. The gap was a visible sheet and one automated payment.
This week, fill one page with every balance, minimum and due date. Then schedule the first extra payment. A steady paycheck fits a fixed amount. A paycheck that moves fits a lower floor plus a sweep of each side payment.
Go back to the number I opened with. $67,000 over thirty-six months is $1,861 a month, and that schedule began as one page of balances on my kitchen table. Make yours this week.
Your first move is one page
List every debt with its balance, minimum and due date tonight. Then schedule the first extra payment for your next payday.
1 thought on “I Paid Off $67,000 of Debt in 3 Years on a Teacher’s Salary — Here’s the Exact Plan”