How do I organize all of our family financial accounts, insurance policies, and passwords into one place before an emergency happens? This guide settles that exact question by walking you through building a physical family money binder in a single weekend. Most households keep their life spread across a dozen passwords and random desk drawers.
When a sudden crisis hits, that scattered setup turns into a real panic. You waste precious hours searching for account numbers while bills sit unpaid. That confusion costs real money in late fees and missed payments.
This is for any household tired of guessing where documents live. By Sunday night, your partner will find every policy without asking you a single question.
We will map out your exact cash flow, gather your insurance papers, and lock down your passwords. You will spend about four hours total across two days to finish the entire project. Your household will have total clarity before next week starts.
🎯 THE SHORT ANSWER
The Quick Answer
A family money binder is a physical three-ring binder holding printed summaries of every bank account, debt, insurance policy, and utility login. It takes about four to six hours to assemble over one weekend, and its entire purpose is to ensure your partner can run the household finances instantly if you are unable to do so.
Why Fragmented Finances Put Your Household at Risk
Gather every paper statement into one pile today. That stops the chaos.
Most couples assume their digital footprint is easy to trace, but sharing fifteen different passwords across separate portals traps the surviving partner in a maze. A physical binder bridges that gap instantly. Paper needs no login. Paper needs no power.
Open a blank folder. Put your cash totals inside. Do it now.
📂 2 quick taps · about 20 seconds
Find Your Binder Starting Point
Get a custom recommendation for what to tackle first based on your current household setup.
Start with this question
- Where do your household passwords and account logins currently live? Spread across different browser vaults · Scattered on sticky notes and paper
Then read the part written for you
- Start With the Master Password Sheet — Your immediate priority is consolidating access credentials into a secure printed format before gathering statements. 1 page Read: Gathering Your Essential Hardware and Supplies →
- Start With Daily Cash Flow and Bank Accounts — Focus first on checking accounts, automated bill pay schedules, and primary debit card locations. 3 accounts Read: Mapping Your Daily Cash Flow and Bank Accounts →
- Start With Insurance and Debt Policies — Jump straight to consolidating loan numbers and insurance policy declarations so nothing lapses. 5 policies Read: Consolidating Insurance Policies and Debt Obligations →
Gathering Your Essential Hardware and Supplies
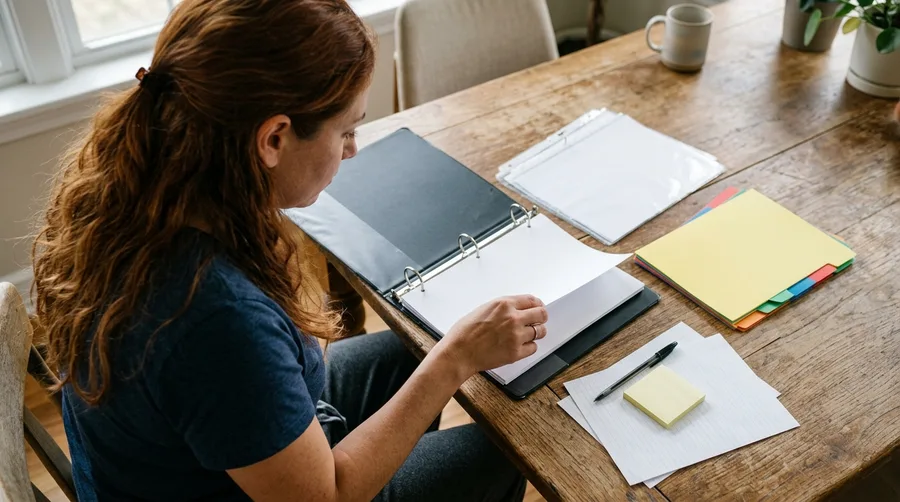
Most people grab a random folder from the desk drawer and hope for the best. That folder falls apart by month three.
You need solid tools instead. Buy a heavy-duty two-inch three-ring binder, twenty durable plastic sheet protectors, and a set of color-coded tab dividers. Spend about $25 total. That small setup protects your paperwork for years.
Good gear stops you from quitting. Loose paper tears easily.
Plastic sheets keep spills away from your tax forms and deeds. Grab a pack of sticky notes and a black pen before you sit down at the kitchen table.
Store the finished book safely. Buy a small fireproof lockbox or place it inside your home safe. It costs around $40. That keeps your sensitive records secure from fire and water damage.
⚠️ COMMON MISTAKE
Avoid Digital-Only Binders
Saving everything in a shared cloud folder defeats the primary safety net of a family binder. If the internet drops or passwords lock out during an emergency, digital files become completely useless.
Mapping Your Daily Cash Flow and Bank Accounts
Do you know every bank account your household owns right now?
Start your Saturday morning by listing every active checking, savings, and money market account in your name. That is a bank account that often pays a higher interest rate than normal. You need to write down 3 specific details for each one. Record the institution name, the account type, and the last four digits of the number. That keeps it safe.
People often confuse this step with closing old accounts you no longer use. They are completely different tasks. This step is only about finding and listing what is active today.
Never write full account passwords directly on these sheets. That is a major security risk. Instead, note where your password manager master key is stored securely.
List every automatic monthly draft right now. That shows your spouse which bills clear on which dates. Open your spreadsheet and log the first draft today.
Weekend Supply Investment
Consolidating Insurance Policies and Debt Obligations
Searching through twenty different digital folders while an emergency unfolds costs your household precious hours when every minute counts. People often keep their auto loans, credit cards, and insurance policies scattered across various email inboxes and online portals. That simple disorganization can delay critical claims payouts by three to four weeks when you need cash the most.
Move next to your liabilities and protection policies. Print the declaration page for your homeowners, auto, term life, and health insurance policies. Include the policy number and agent contact details for each one right on the front sheet. Knowing who to call first saves hours of frantic searching.
List every outstanding debt including mortgages, car loans, and student loans with their respective login portals and balances. Write down the exact website login link and customer service phone number for each account. This single step prevents missed payments if a primary card or statement gets lost in the mail.
Take thirty minutes this Saturday to gather these documents into one physical folder. Put that folder in a known desk drawer so anyone in your home can find it instantly.
Exact Details Needed per Account
Documenting Investment Portfolios and Retirement Accounts
People think investment records sort themselves out online. They do not.
List every retirement plan you hold. That is a tax-advantaged account meant for your later years. Include your work plan and a traditional individual retirement arrangement. That is a retirement fund you fund yourself with pre-tax dollars. Add a Roth individual retirement arrangement. That is a retirement fund you fund with taxed dollars so it grows tax-free.
Write down the firm name, the account digits, and who gets the money if you die. Outdated names cause huge court delays. Check those forms today. Make sure they match your life now.
Beneficiary Review Math
Assumes a standard household asset review every 2 years
Cataloging Monthly Bills and Utility Subscriptions
Bills arrive from everywhere.
You receive them via email, autopay, and physical mail.
Gather eight active recurring charges spanning utilities, internet, and phone plans.
List the service provider, average monthly cost, billing date, and the funding source or credit card attached.
This directory stops unwanted subscription charges immediately if a card needs replacement.
It costs you $120 a year in forgotten fees when cards expire.
A single master list prevents that waste.
It also gives your spouse a clear picture of fixed monthly cash outflows.
Take thirty minutes this week to write down every recurring bill on a single sheet of paper.
🗓️ Your Weekend Build Schedule
Saturday Morning
Gather all physical bank statements, insurance papers, and loan documents in one pile.
Saturday Afternoon
Insert plastic sheet protectors and label the five core tab dividers.
Sunday Morning
Write down account numbers, contact details, and recurring bill schedules.
Sunday Evening
Review the completed binder with your spouse and place it in the safe.
Establishing the Semi-Annual Review Routine
A binder left alone for twelve months is out of date.
The true cost of this plan is two hours of your time twice a year.
You spend that time to save days of stress later.
Set a phone alert for June and December to open the book and check each page.
Tear up old bills so your mail stays safe.
Do that check this weekend.
Jargon, decoded
Frequently Asked Questions
Should I write down my actual account passwords inside the physical binder?
No. Writing raw passwords creates a severe security risk if the binder is misplaced. Instead, write down the name of your password manager and where the master key is securely stored.
Where is the best place to store the finished family money binder?
Store your completed binder inside a home fireproof safe or a secure lockbox. Make sure your spouse knows the combination or exact location of the key.
How often should I update the financial details inside the binder?
Review and update all pages every six months. Set a recurring calendar reminder to swap out old statements and verify current insurance coverage.
What if my spouse refuses to look at the binder?
Keep the initial review casual over a weekend morning coffee. Walk through just the bank account tab first so it feels manageable rather than overwhelming.
Do I need special software to format the financial pages?
Standard printer paper and a basic pen work perfectly. You do not need fancy design software or expensive templates to build a functional household binder.
Securing Your Household Paper Trail for the Long Run
Write down one essential number on the inside cover this weekend: the total sum of your liquid cash across all regular savings accounts.
If that total sits below five thousand dollars, make building a basic cash buffer your very next step after the binder is closed.
A single weekend of focus removes household guesswork forever. Grab a thick ring binder this Saturday morning and print out your first blank page.
Ready to build your binder this weekend?
Review your bank accounts and insurance policies today, then gather your supplies to map out your family financial safety net.