Two families earn the exact same income, buy identical homes in the same neighborhood, and carry similar savings balances. When an unexpected medical emergency hits the primary earner, the first family sails through weeks of hospital decisions without a single legal roadblock. The second family spends thousands in probate court just to access joint funds for mortgage payments.
The difference has nothing to do with wealth or luck. It comes down to a binder of signed legal papers that most adults put off until their sixties. Waiting until a health scare or retirement forces your hand leaves your family vulnerable to court delays and frozen accounts.
You do not need an army of attorneys or a multi-million-dollar estate to protect your household. You need eight specific legal documents in place before you turn fifty. Each one solves a distinct problem that courts handle poorly on your own.
This guide walks through every required form, explains what it actually does in plain English, and shows you how to get them sorted without spending a fortune on hourly retainers.
🎯 THE SHORT ANSWER
The Short Answer
Every family needs eight core documents before age fifty: a durable financial power of attorney, a medical power of attorney, a living will, a last will and testament, a HIPAA release form, a minor guardianship designation, a revocable living trust for real estate, and a comprehensive asset inventory list.
Why Turning Fifty Changes the Legal Math Entirely
Time moves fast.
Your twenties and thirties are about building a career and stacking your first savings. Once you cross fifty, the risk profile of your household changes completely. Minor children are growing up, retirement accounts are compounding past six figures, and aging parents may soon need financial oversight. That is compound interest working in reverse for your risks.
That means money builds up faster over time, but so do the legal complications if something goes wrong. Courts do not care about your intentions if you become incapacitated. State default laws dictate who controls your money and raises your children instead.
That court process takes months and costs families an average of $3,500 in legal fees. It often places your children in temporary state foster care while judges deliberate.
You can fix this gap this week by listing your assets and checking your beneficiary forms.
🧭 2 quick taps · about 20 seconds
Find the Documents Your Family Needs Right Now
Answer two quick questions about your household to jump straight to the paperwork that matters most for your stage of life.
Start with this question
- Do you currently have minor children living at home? Yes, we have kids under 18 · No minor children
Then read the part written for you
- Full Protection: Wills, Trusts, and Guardianships — Because you own property and have children, your top priorities are naming legal guardians and establishing a living trust to bypass probate entirely. 8 Documents Read: Why You Need a Written Will →
- Essential Health and Financial Powers — Without minor dependents, your immediate focus should be locking down medical and financial powers of attorney so a partner can step in during emergencies. 5 Core Forms Read: Medical Power of Attorney and HIPAA Release →
- Core Documents Minus Real Estate Trusts — Renting simplifies your asset structure, but you still need guardianships, wills, and strong medical directives to protect your income and family. 6 Essential Forms Read: Guardianship Designations for Minor Children →
Medical Power of Attorney and HIPAA Release
A medical power of attorney names someone you trust to make healthcare decisions if you are unconscious or incapacitated.
Without this document, doctors cannot legally discuss your condition with your unmarried partner or adult children. That is a hard wall. Hospitals face legal limits every day. They cannot guess your wishes.
Federal privacy laws prevent medical staff from sharing records without explicit written consent. Stuart, an illustrative man of forty-seven, learned this rule when his partner ended up in the emergency room after a crash. Staff shut the door. They needed a signed form. He could not get updates for six hours.
That single missing signature cost $2,500 in court fees and delayed care while a judge sorted out who had the right to speak. It was a painful week. Money went to paperwork instead of healing. You can stop that outcome entirely.
Pair your power of attorney with a signed Health Insurance Portability and Accountability Act release form to ensure seamless communication during a crisis. That is the extra paper you need. It grants open access to charts and doctors.
The trade-off is giving someone else total control over your care choices. It feels heavy to sign. But the alternative is leaving your medical team with no clear voice to guide them. Pick one person and talk to them this week. Download the state form online, print it out, and sign it before a notary.
⚠️ COMMON MISTAKE
The Spousal Access Trap
Many people assume marriage grants automatic medical decision-making rights. In an emergency, hospitals often demand court-certified paperwork before granting access to medical records.
Why You Need a Written Will
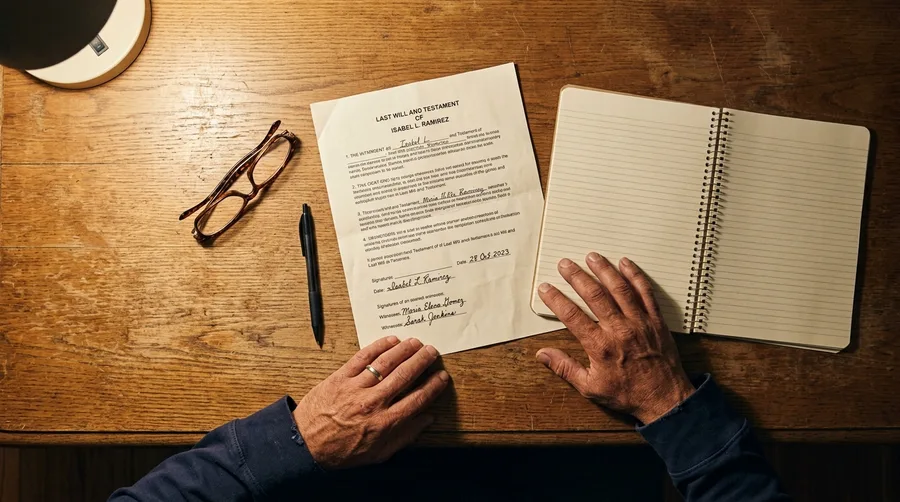
Most people assume the state hands everything to a surviving spouse automatically after someone passes away. That assumption is false.
Dying without a will means state law decides how your bank accounts and belongings are divided up. State rules split those assets between a spouse and children in fixed shares that rarely match what you actually want.
Drafting a last will and testament replaces that rigid legal process with your exact choices. You name who gets what down to the last dollar.
Set aside two hours this weekend to list your accounts and talk to an estate attorney. Getting this document in place costs about $300 and takes the guesswork out of tomorrow.
Guardianship Designations for Minor Children
Eighteen is the age when courts stop needing someone to raise your kids. If you skip this choice, a judge steps in to decide who takes your home and children.
That stranger knows nothing about your family rules or values. You fix this by naming a primary choice and a backup in your will.
Talk to them before you sign anything. This week, pick two people who share your values and ask if they are ready to help.
Guardianship Selection Criteria
Durable Financial Power of Attorney
People assume a spouse automatically has the legal right to sign checks or pay bills for an incapacitated partner. That is false. Banks freeze accounts until a judge grants official access.
A durable financial power of attorney stops that mess. It names a trusted person to handle cash and property if you cannot. Without it, family members spend $5,000 in court fees just to pay the water bill.
Talk to your choice this week and ask if they accept the duty. Then have a lawyer draft the form.
Scenario Compare: Two Families in Crisis
How having a financial power of attorney changes an emergency outcome.
Living Wills and End-of-Life Directives
People assume a standard will covers medical emergencies. It does not. A living will takes over only when you cannot speak.
This document spells out your exact medical wishes for a terminal condition. It removes the crushing burden of guessing from your spouse or children.
As an illustrative example, Stuart, 47, a man reviewing his files realized that doctors need explicit written limits. He specified that he wants comfort care only, avoiding 30 days of unwanted mechanical ventilation.
You must choose among ventilators, tube feeding, or pain management. That clarity protects your family from agonizing courtroom fights.
Because these choices depend on state medical rules, talk to a local elder law attorney. Put copies with your doctor this week.
Living Will Directives — At a Glance
🫁 Ventilator Use
Specify limits
🍲 Feeding Tubes
Define duration
🩺 Pain Relief
Comfort priority
📋 Storage Location
Doctor and proxy
Core purpose
Removes guesswork for family members during heartbreaking medical decisions.
Revocable Living Trusts for Real Estate
A revocable living trust is a legal arrangement that holds ownership of your home while you keep total control during your life.
Consider Stuart, an illustrative 47-year-old homeowner whose house is worth $400,000. Without a trust, a probate court handling that real estate takes an average of 12 months and 5% in fees, which totals $20,000 lost. A trust cuts that settlement time down to just 3 weeks and keeps every dollar in the family.
The next action is to speak with a local estate attorney about drafting the trust deed and filing the property transfer this month.
Living Trust Key Facts
Asset Inventory and Digital Account Lists
Gather every single account paper and digital file you own into one master list before the year ends. People often confuse this list with a simple budget sheet, but a budget tracks monthly spending while an asset inventory maps out every dollar you actually own. Stuart, 47, an illustrative example of a man organizing his family paperwork, spent three full weekends trying to find old retirement plans across four different jobs.
That is forty hours of searching your family will have to do alone if your records stay scattered.
Executors waste hundreds of hours hunting down lost money.
Your family cannot claim money they do not know exists.
Write down every bank name, policy number, and storage vault location in one secure place. Keep it locked safely.
Review this page every January to keep the map current.
Do it today.
Frequently Asked Questions
How much does a complete estate plan cost with a lawyer?
A comprehensive package covering all eight documents typically ranges between $1,000 and $2,500 depending on your location and asset complexity. This investment saves tens of thousands in future probate fees.
Can I write my own will using online legal software?
Online templates work well for simple, single-person estates with minimal assets. Families with minor children, real estate, or complex financial holdings should always work with a qualified estate attorney.
What happens if I die without a will in place?
Dying without a will means your state determines how your property is divided through intestate succession laws. A judge also decides who becomes the legal guardian of your minor children.
How often should I update my estate planning documents?
Review your documents every three years or immediately following major life events such as marriage, divorce, the birth of a child, or purchasing a new home.
Do living trusts completely replace a last will and testament?
No, living trusts hold specific assets like real estate, but you still need a pour-over will to catch any remaining property and legally designate guardians for your minor children.
Safeguarding Your Family's Financial Future
Organizing these eight documents requires an upfront investment of time and money, but it buys priceless peace of mind.
Your family will not have to guess your wishes or fight courts to pay household bills during a crisis.
Legal paperwork cannot predict every twist life throws your way, but it ensures your household remains protected no matter what happens.
Speak with a qualified professional this month and get your paperwork sorted before you turn fifty.
Ready to Secure Your Household?
Review our 4-week roadmap above and take the first step by listing your assets this weekend.