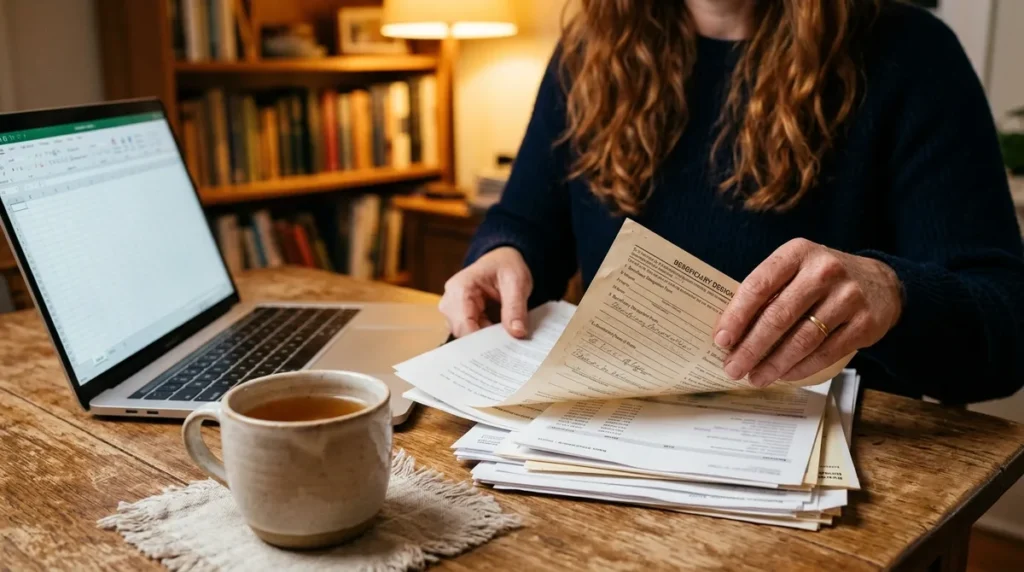
I spent three years assuming my legal will protected every dollar in my bank accounts. It did not. Your bank and retirement accounts do not care what your will says.
A single name on an old form overrides every instruction you wrote with a lawyer.
If you opened a 401(k) twenty years ago and forgot to update the page, a former partner could inherit $250,000 while your kids get nothing. That mistake costs families millions of dollars every year in lost assets and legal fights.
This guide shows how contract law beats probate court, and how to fix every account in sixty minutes. You will find the exact steps to audit your named heirs in the third section below.
Check your accounts today.
🎯 THE SHORT ANSWER
Can a beneficiary form override a will?
Yes, absolutely. Contract law governs retirement accounts, life insurance policies, and payable-on-death bank accounts directly. When you pass away, the financial institution distributes those funds immediately to the named person on file, ignoring completely what your formal will dictates.
Why Contract Law Always Beats Probate Court Orders
Most people assume your final wishes live safely inside your signed will.
They do not.
Your last will and testament must go through probate court before any property gets distributed to your heirs, which can tie up your estate for up to a year and cost thousands in court fees.
Beneficiary designations bypass the probate process completely because they act as direct legal contracts between you and the financial institution holding the assets.
When you name someone on a retirement form, you sign a binding agreement stating that the institution must pay that specific individual upon your death.
Courts consistently rule that these private contracts take legal precedence over a generalized last will written years later, meaning an old form wins over a new document every single time.
Imagine a retirement account holding $250,000 that lists an ex-spouse from a decade ago, while your brand-new will leaves everything to your current family.
The court will award the entire $250,000 to the ex-spouse because the contract on file with the bank overrides the instructions written in the will.
Understanding this fundamental division prevents catastrophic estate planning failures.
Log into one retirement account or insurance policy this week to check the name printed on the beneficiary line.
📋 2 quick taps · about 20 seconds
Find your beneficiary action plan
Identify your exact document risk in two quick taps.
Start with this question
- When was the last time you updated your retirement account designations? Over five years ago · I have never checked them · Within the last year
Then read the part written for you
- High Risk: Outdated or Missing Forms — You likely have zero documentation on file or your employer plan lists an old relative. Your current will cannot protect these assets. 100% Read: The Costly Trap of Outdated Designations →
- Low Risk: Current Records — Your paperwork matches your current intentions. Focus on establishing a regular review calendar to keep it that way. 1 Year
- Critical Risk: Conflicting Intentions — Your past spouse or deceased relatives may still be legally entitled to your funds. Immediate corrective action is required. Immediate Read: Aligning Your Beneficiaries With Your Current Will →
- Moderate Risk: Secondary Check Needed — Even without life events, financial institutions often lose older records during database migrations. Confirm your current status online. 5 Mins Read: How to Audit Every Account This Week →
The Costly Trap of Outdated Designations
Millions of people pick a beneficiary at age twenty-five. They never look at the paperwork again.
Time passes. Marriages end, children are born, and former partners stay attached to six-figure balances.
If you pass away with an ex-spouse listed on your retirement account, the bank must send the money to them. Your new spouse cannot sue to change this outcome. The contract wins.
That is a severe penalty for ignoring old paperwork. It takes less than one hour to check every account provider you use. Log in today and look at the names listed on your forms.
Key Estate Terms Decoded
How to Audit Every Account This Week
Open your notebook now.
You own more accounts than you think.
Grab a pen and list every single financial asset you own today.
Include your workplace plan, your individual retirement accounts, and your term life insurance policies.
Most people hold about 4 accounts across different banks and past jobs.
That is $45,000 in average balances sitting behind old passwords.
Log into each provider portal and check your profile settings.
Find the beneficiary designation section hidden under account services.
This simple check takes 15 minutes per account.
It prevents a total legal mess for your family later.
Download the confirmation page showing your current choices for your permanent records.
⚠️ COMMON MISTAKE
Never name minors directly
Naming a minor child as a direct beneficiary forces the court to freeze the funds in a blocked account until they turn eighteen. Always establish a proper trust or name a custodian under the Uniform Transfers to Minors Act instead.
The Danger of Ignoring Contingent Designations
Name a backup choice for every account you own right now. Primary designees get the funds first, but what happens if that person passes away before you do?
If you left the secondary or contingent section blank, your assets fall back into the probate system by default. That oversight triggers unnecessary court fees and delays distribution by six months or more.
Always name at least one backup person to keep your money out of court. Log into your accounts this week and fill in those empty secondary lines.
The True Cost of Probate Delay
Estimated financial impact of court-routed assets on a $500,000 portfolio
Aligning Your Beneficiaries With Your Current Will
You likely believe your will controls who gets your money when you die. That assumption costs families millions of dollars every year in avoidable legal battles.
Contract law always overrides probate court orders. If your will splits your savings equally three ways, but your retirement account names your brother alone, your brother receives one hundred percent of that balance.
Pull out your legal paperwork and your account documents this week. Verify that every single name and percentage matches word for word across both files.
Time Investment for Complete Audit
Why Employer-Sponsored Plans Need Special Attention
Workplace retirement plans follow federal law. That means rules are strict. If you are married, your spouse gets one hundred percent of the account by default. You cannot override this law with a quick click on your work portal. Ignoring this rule will ruin your plan instantly.
Your spouse must sign a notarized waiver to change this. That takes actual effort. The trade-off is annoying paperwork for legal safety. Do not skip it. Call your human resources office this week and ask for their specific spousal consent form.
Best Practices for Account Designations
Frequently Asked Questions
Does a new marriage automatically update my old retirement account beneficiaries?
No. Marriage does not automatically alter existing contract designations on individual accounts. You must log in and update the paperwork manually to include your new spouse.
What happens if all my primary and contingent beneficiaries pass away before me?
If no living designees remain, the asset defaults to your estate. That triggers the probate court process and subjects the funds to your will or state intestacy laws.
Can I name a living trust as the primary beneficiary of my IRA?
Yes, naming a trust is common for complex estate planning needs. However, tax rules for inherited IRAs change significantly when a trust is named, so consult a CPA first.
How often should I review my financial account designations?
Check your paperwork at least once a year, or immediately following any major life milestone such as marriage, divorce, the birth of a child, or a family death.
Where can I find the beneficiary form for my old 401(k) from a past job?
Contact the plan administrator or human resources department of your former employer. They will mail or email you the current form on file for your review.
Setting Your Annual Beneficiary Review Date
Set a calendar reminder right now for the same weekend every autumn. Pick October 1st. Linking this task to an annual routine makes sure you never forget it.
When that review date arrives, log into your accounts and check two specific items. Confirm that your primary beneficiary matches your current family setup, and verify that you named a living contingent choice as your backup.
A missing backup name sends the money straight to probate court if your main choice passes away before you. Taking twenty minutes each fall prevents a costly legal battle for the people you love.
Update your records this weekend.
Audit Your Accounts Today
Log into your primary retirement portal right now and check your active beneficiary form before closing this tab.