Carrying thousands in consumer debt into your late forties quietly steals hundreds of dollars every month in interest payments that buy you nothing.
That money could have funded retirement accounts, emergency reserves, or simple peace of mind.
Most guides treat personal finance like a textbook, but real financial stability usually comes from changing a handful of daily routines rather than studying complex market theories.
Renee is an illustrative composite built from typical household financial data, facing the exact debt totals and income levels common to many thirty-year-olds.
We will break down the exact choices that moved the needle, starting with the core math and working through the twelve practical habits.
🎯 THE SHORT ANSWER
The Core Answer
Becoming debt-free by age 48 requires automating transfers and stopping lifestyle inflation immediately, rather than waiting for a large salary increase.
The Central Calculation That Changes Everything
Fifteen thousand dollars is the average balance weighing down cards when people finally decide to look closely at their statements.
If you carry that amount at an average interest rate of 20%, you are paying $3,000 every year just in finance charges.
That is $250 every month vanishing into thin air before you buy a single grocery item or pay a utility bill.
Understanding this math turns debt repayment from a vague chore into an urgent financial rescue mission, and when money gets tight later, you scale down your extra payments rather than stopping entirely so you never lose your progress.
🧭 2 quick taps · about 20 seconds
Find Your Starting Point
Select your primary financial hurdle to jump straight to the habit you need right now.
Start with this question
- Which of these feels like your biggest immediate financial drag? High-interest credit card balances · Saving nothing at the end of the month
Then read the part written for you
- Build a Starter Buffer First — Stop aggressive debt paydown just long enough to secure a small cash buffer so a broken appliance does not force you back onto plastic. $1,000 Read: Stop Spending Unconsciously →
- Automate Your Savings Transfers — If money stays in your checking account, it tends to disappear. Move savings the day your paycheck arrives. 10% Read: Set Up Automatic Savings Before You See the Money →
- Attack the Debt Avalanche — Direct every spare dollar toward the highest interest rate balance while maintaining minimums on the rest. 20% Read: Target High-Interest Balances First →
Stop Spending Unconsciously
Every month starts with good intentions.
Small daily purchases drain accounts before bills are paid.
Renee is an illustrative composite with realistic numbers, not a real client.
Renee realized at age 32 that small dining out habits cost nearly $400 every month.
That is real money slipping away.
Tracking every single dollar for thirty days exposes the exact leaks in your spending.
Write down your fixed bills, debt minimums, and flexible spending to see where your money actually goes.
Look at your bank statements from the last thirty days.
Add up every single coffee, lunch, and ride share.
The total will surprise you.
That is the first step toward keeping more of what you earn.
Pick one category to trim this week.
The Cost of Carrying a Balance
Based on a $10,000 balance at 22% APR making minimum payments
Set Up Automatic Savings Before You See the Money
Relying on willpower to save money fails almost every time. That is a plain fact.
Most people wait until the end of the month to save what is left over. Usually, nothing is left.
Set up an automatic transfer that moves money into a separate savings account on payday. For Renee, who earns $3,000 a month, moving $150 out immediately leaves $2,850 for the month. That is 5% saved before spending starts.
When the cash is gone right away, daily habits adjust. You just spend less without thinking about it. Treat this transfer like a monthly utility bill that must be paid.
Log into your bank app today and schedule a $50 transfer for your next payday. If that feels too tight, start with $20. A small amount saved every single month beats a large amount you only save sometimes.
Best Accounts for Your Savings
Target High-Interest Balances First
List every debt by its interest rate from highest to lowest before you pay another penny toward the rest. Not all debt is equal, and paying off a low-interest loan while credit cards accumulate twenty percent interest stalls progress completely. That is a costly mistake that keeps people stuck for years.
Throw every extra dollar at the top balance while paying the minimums on the rest of your accounts. Renee owes three thousand dollars on a credit card at twenty-two percent interest and fifteen thousand dollars on a car loan at four percent. She puts an extra two hundred dollars toward the card every month.
That extra payment cuts her payoff timeline by two full years and saves over one thousand dollars in interest charges. Once the first card is cleared, roll its entire monthly payment into the next target on your list.
Live Below Your Means After Raises
Getting a pay raise is exciting, but increasing your spending to match it keeps you trapped in the paycheck cycle forever. Every single time your income rises, lifestyle inflation quietly swallows the difference before you even notice.
When Renee received a promotion at age 35, her salary bumped up by $10,000 a year. She chose to keep her living expenses exactly level instead of buying a newer car or a larger apartment.
Every extra dollar from that raise went directly toward paying down remaining balances and building investments. That choice alone accelerates your path to financial freedom by a decade.
The math is simple. If you save the entire raise, your savings rate doubles overnight. That is the power of a frozen lifestyle.
Your next action is simple. When your next pay raise hits, redirect the entire difference into your savings account before you see it in your checking balance.
💡 PRO TIP
The Half-Raise Rule
When you get a raise, commit half of the net increase to your lifestyle and funnel the other half directly into savings or debt repayment.
Build a Buffer Before Investing
What stops a solid investing plan from surviving its first year?
Jumping straight into the stock market without cash reserves creates a dangerous vulnerability. That is the risk of rushing.
One unexpected car repair forces you right back onto high-interest credit cards. That breaks your momentum.
Keep at least one thousand dollars in a high-yield savings account before directing funds elsewhere. That is an account paying much more interest than a standard bank.
This small buffer protects your long-term progress from short-term disruptions. Move that cash today.
Emergency Fund Targets — At a Glance
🪙 Starter Goal
$1,000 cash
📅 Full Reserve
3 to 6 months
🏦 Location
High-yield account
Rule of thumb
Never invest extra cash until your starter buffer is fully secured.
Review Subscriptions and Fixed Costs
People assume subscription creep happens because life is expensive, but it actually happens because bills are quiet. A monthly charge of $15 or $20 slips past notice on a bank statement because it looks like noise rather than a leak. Renee, an illustrative composite with realistic numbers, found she was paying $145 every month for tools and media she had not opened since spring.
That is $1,740 a year vanishing into inactive software and unused streaming tiers. The reason these charges survive is that companies rely on inertia and forgetfulness to keep collecting. Auditing your recurring bills twice a year stops that quiet drain before it grows.
Look at your last two bank statements and highlight every single line item that repeats on a monthly schedule. Cancel anything you have not touched in the last thirty days without hesitation. If you truly miss a service, you can always sign up again later, but most of them will not be missed at all.
Take the freed-up $145 and send it straight to your primary debt balance. That single shift shortens your payoff timeline and puts your actual cash back toward what matters.
Where Monthly Subscription Creep Goes
Master the Forty-Eight Hour Rule
Impulse buying is the enemy of steady debt repayment and long term wealth building. When you feel the urge to purchase a non essential item online or in a store, force yourself to wait forty eight hours.
Put the item in your online cart and walk away from the computer. Most of the time, the urge fades completely once the emotional spike passes. If you are looking at a sweater that costs $80, walking away stops the money from leaving your checking account immediately. That money stays where it belongs while your brain cools down.
The mistake people make is believing that willpower alone will stop them from spending money on things they do not need. Willpower runs out by Tuesday afternoon when you are tired from work. A system like a mandatory waiting period works because it lets time do the heavy lifting for you.
When the forty eight hours pass, check your bank balance to see if the purchase still makes sense alongside your rent and grocery bills. If you still want the item and have the cash saved, you can buy it without regret. Your next action is to open your favorite shopping apps right now and turn off one click purchasing so you always have to type your card number out by hand.
Establish a Weekly Money Date
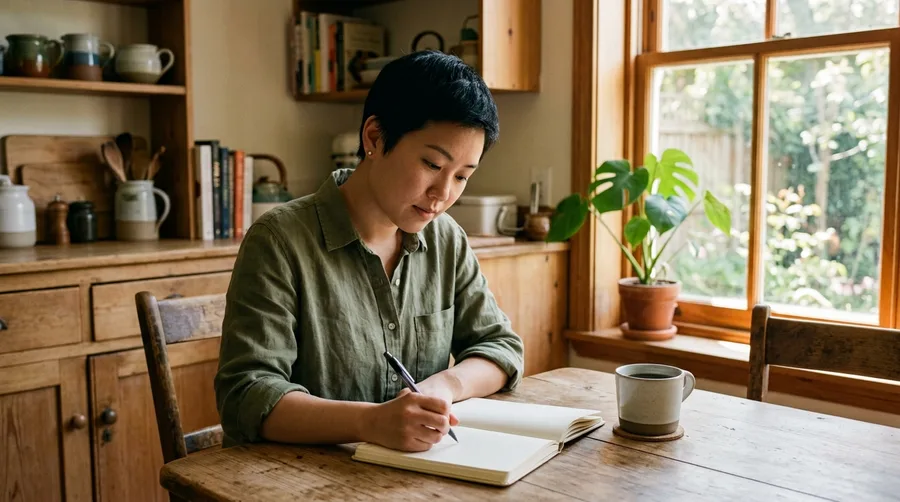
Fifteen minutes. That is all it takes to change how money feels in your hands.
Ignoring your bank accounts creates anxiety that leads to even worse spending choices. When you avoid looking at the numbers, small problems turn into big surprises because fear keeps you in the dark.
Spend fifteen minutes every Sunday morning looking over your balances, upcoming bills, and recent transactions. That weekly review takes the panic out of the process and turns money management into a calm, regular habit.
Renee, an illustrative composite with realistic numbers, made this weekly check-in a relaxing routine with a cup of coffee. Instead of dreading the screen, she paired the task with something comforting so it felt like self-care rather than a chore.
Knowing your exact numbers eliminates financial surprises and keeps your goals on track. You cannot fix a leak if you refuse to look at the floor.
Take your next action this coming weekend. Pick a specific time on Sunday, pour your drink, and open your banking apps without judgment.
Learn to Say No Without Guilt
Why do social outings cost hundreds of dollars when all you wanted was to catch up with a friend? Social pressure drives a massive share of unnecessary consumer spending that ruins a monthly budget.
Consider what happens when you say yes to three $75 restaurant dinners every month. Three dinners multiplied by $75 equals $225 spent every month. Over twelve months, that exact choice costs $2,700 of your hard-earned cash. That money could clear a high-interest credit card balance instead.
True friends respect your honesty when you focus on financial goals right now. Propose low-cost alternatives like cooking dinner at home or meeting for a weekend walk. Text a friend today with a free alternative plan.
Negotiate Your Fixed Household Bills
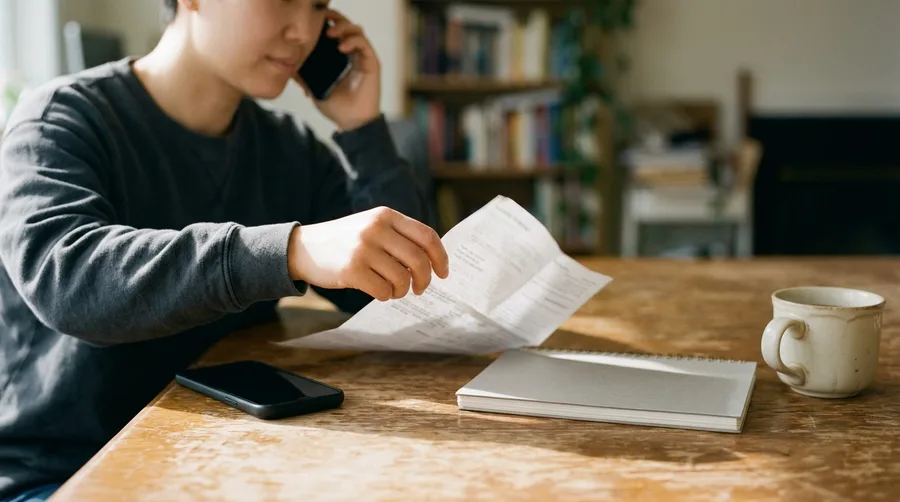
People assume utility, insurance, and internet bills are set in stone, but providers often offer unadvertised rates.
Call your internet service provider or insurance agent once a year to ask for loyalty discounts.
Comparing local rates takes twenty minutes and can shave $50 off your monthly overhead.
Redirect every dollar of savings directly toward your debt payoff fund.
Track Your Net Worth Monthly
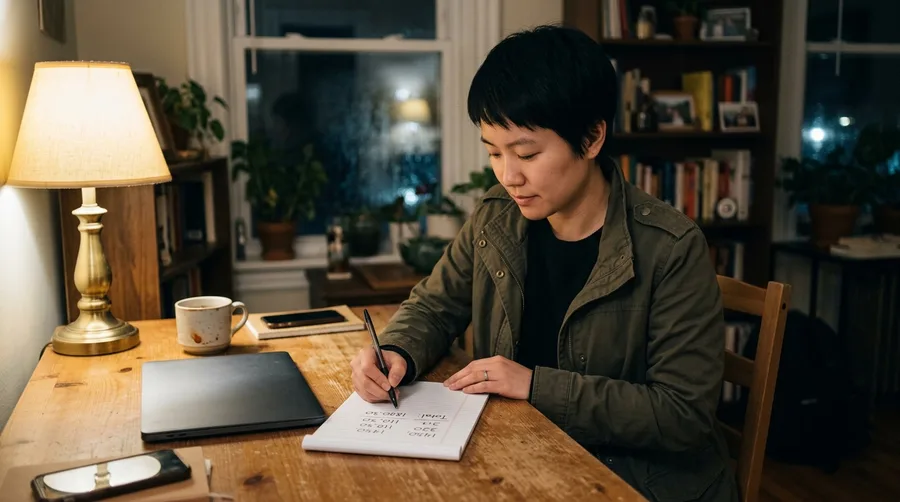
Focusing only on monthly budgets can feel exhausting if you cannot see the big picture.
Calculate your net worth on the first of every month by subtracting your total debts from your total assets.
Seeing that number climb upward provides powerful psychological momentum.
Even when progress feels slow, watching debt shrink month after month builds undeniable confidence.
Frequently Asked Questions
How long does it take to become debt-free following these habits?
The timeline depends on your total debt amount and income level, but most households see dramatic progress within three to five years of consistent execution.
Should I stop investing while paying off credit card debt?
Yes, high-interest credit card debt at 20% APR acts like a negative investment that outpaces typical market returns. Clear high-interest balances first.
What is the best way to handle unexpected expenses during debt payoff?
Maintain a starter emergency fund of $1,000 in cash before aggressively paying down debt so you never have to use credit cards for emergencies.
How often should I review my monthly budget?
Dedicate fifteen minutes every week to check your accounts and track spending to catch leaks early.
Replacing the Scarcity Mindset With Intentional Control
Carrying debt for decades teaches you that money is something that happens to you rather than something you manage.
Building these twelve habits turns that feeling around completely.
You stop reacting to monthly bills and start directing every dollar toward the life you actually want to build.
Start Your Weekly Money Review
Take fifteen minutes this Sunday morning to open your accounts and track your spending.